Why Modern Monetary Theory Is Not Factual — Expanded Evidence from Institutions, Data, History, and Formal Tests
Modern Monetary Theory (MMT) presents itself as a neutral description of how currency-issuing governments operate. Its core claims are that such governments cannot run out of money, that spending creates new money while taxes merely destroy it, and that the only meaningful constraint is inflation caused by exceeding real resource limits. These assertions are used to argue that large new spending programs face far fewer obstacles than conventional analysis suggests.
The problem is that several of MMT’s central descriptive claims do not match institutional reality, its inflation framework struggles with observed data, formal empirical tests reject its policy rules, and the approaches associated with it have a repeated record of producing high inflation, currency instability, and falling real wages. Expanding the evidence from multiple independent sources makes the gap between the theory and outcomes clearer.
1. Institutional Reality Versus MMT’s Description of Spending
A foundational popular claim is that every time the federal government spends, it creates new money. In this telling, the Treasury simply instructs the central bank to credit the recipient’s account.
Under current U.S. law and operating procedures, this is not what happens. The Treasury General Account at the Federal Reserve is not permitted to run an overdraft. When the government makes a payment, the Treasury must already hold a sufficient balance; that balance is debited. The transaction is a transfer of existing funds, not the spontaneous creation of new money at the moment of spending.
Money-supply statistics can create the appearance of creation because aggregates such as M1 exclude government deposits. When funds move from the public sector to private accounts, measured private-sector money rises even though the total stock of money in the system has not automatically increased. Critics have pointed this out for years. MMT responses typically shift to the argument that the rules are “self-imposed” and could be changed. Changing the rules is a different claim from asserting that the present system already operates without them.
This pattern — presenting a possible future arrangement as a description of current practice — has led multiple analysts to conclude that popular MMT often functions more as prescription than pure description. A Bank of France working paper by Françoise Drumetz and Christian Pfister concluded that MMT is “more of a political manifesto than of a genuine economic theory,” criticizing it for confusing legal and operational realities and treating central-bank independence as a myth. Other critiques note that the strong claim “governments create money when they spend” under current institutional barriers conflates how the system should work (in MMT’s preferred setup) with how it actually does.
2. Accounting Identities Do Not Equal Real Enrichment
MMT correctly observes that a government financial deficit is matched by a non-government financial surplus. This is an accounting identity. It does not imply that the public becomes richer in real terms.
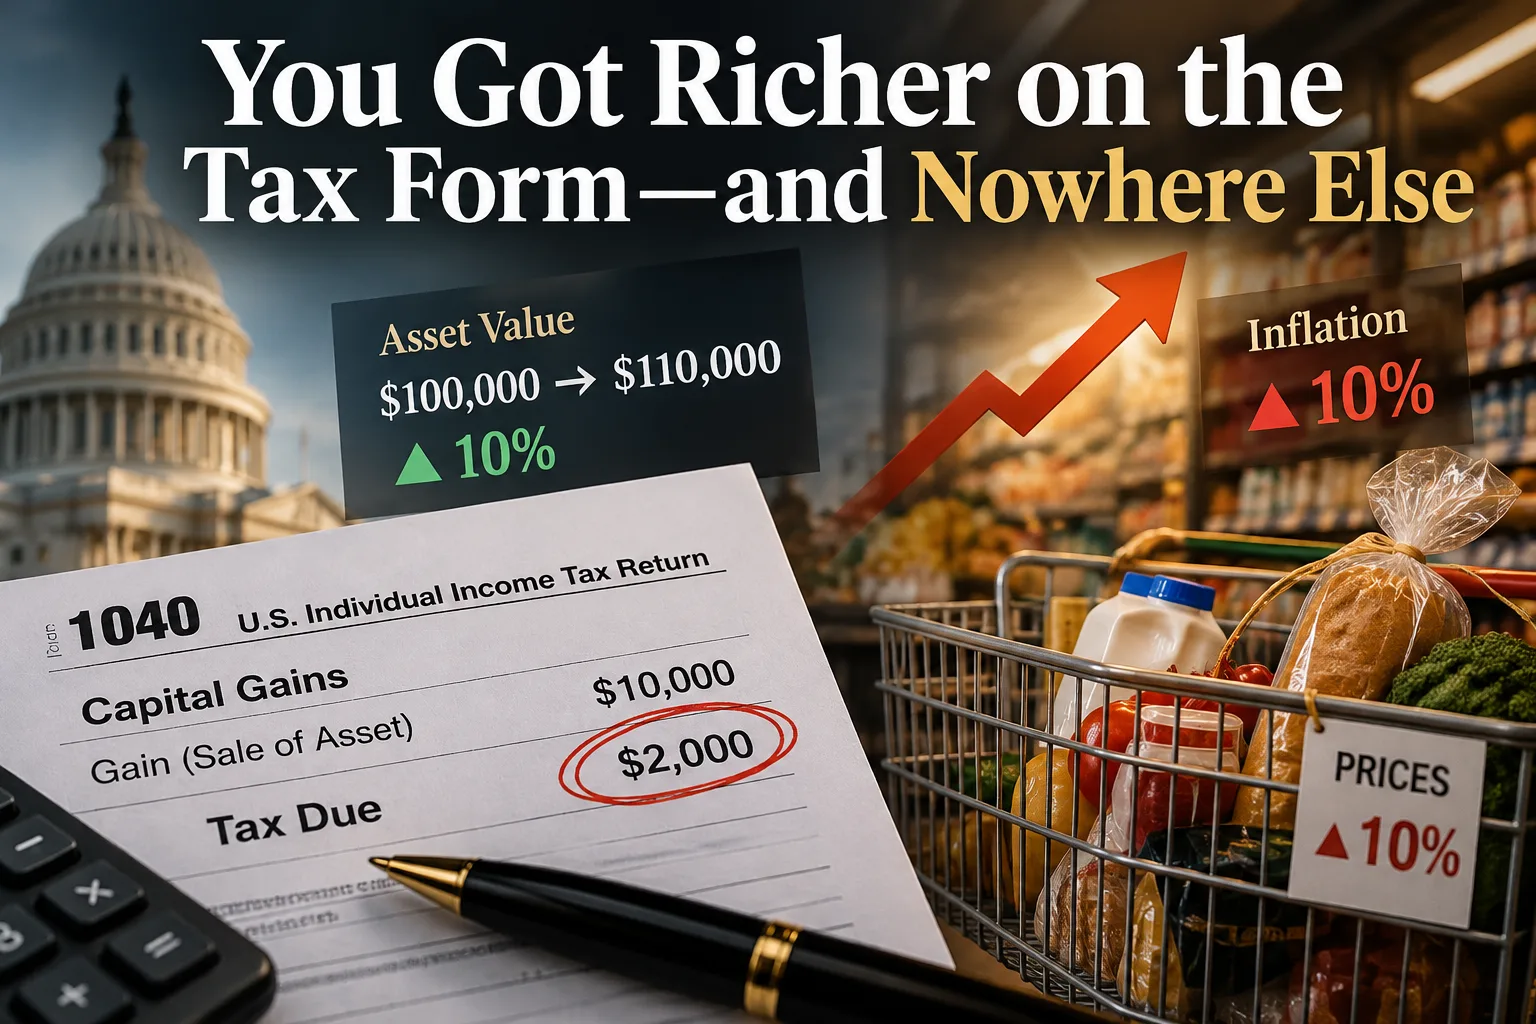
Argentina supplies a long-running illustration. Large fiscal deficits financed in significant part by monetary expansion repeatedly expanded nominal balances. Households accumulated large peso holdings. Real purchasing power did not follow. High and persistent inflation eroded the value of those balances, reduced real wages, and produced repeated crises. Nominal financial wealth rose while real living standards stagnated or declined. When MMT writers carefully insert the qualifier “financial,” they acknowledge the distinction while still allowing the stronger, and false, impression that deficits reliably enrich the private sector.
3. The Inflation Framework Conflicts with Observed Data and Formal Tests
MMT’s inflation theory holds that prices should remain stable while substantial unused capacity exists. Inflation appears, on this view, primarily when spending pushes demand beyond available real resources.
Advanced economies have recorded persistent positive inflation (often near 2 percent) for decades while official measures indicated output gaps or underutilized resources. If large slack truly existed, the theory has difficulty explaining why inflation remained positive rather than near zero. Responses that attribute measured inflation mainly to quality adjustments or relative-price shifts do not fully resolve the inconsistency.
A formal empirical test reinforces the problem. In a 2025 study published in the International Journal of Finance & Economics, Chunping Liu, Patrick Minford, and Zhirong Ou embedded MMT policy rules in a full dynamic stochastic general equilibrium (DSGE) model and tested it against U.S. post-financial-crisis data using indirect inference. The MMT version was rejected by the data. The MMT policy rules also produced a material welfare loss relative to the standard rules, largely because they destabilized output. This is one of the clearest model-based rejections of MMT’s monetary-fiscal coordination claims against actual U.S. data.
The post-2020 inflation episode provided an additional real-time test. Large fiscal expansions occurred in economies that MMT-style analysis often described as still having slack. Inflation rose sharply in many countries, and central banks responded with aggressive tightening. The sequence did not unfold as a clean demonstration that inflation appears only after a clearly identifiable full-employment ceiling is breached.
4. Historical Record of MMT-Style Policy Experiments
The most direct evidence against the optimistic policy implications of MMT comes from repeated historical episodes that combined large fiscal expansions with heavy monetary financing, often justified by claims of idle resources and the absence of genuine financial constraints.
Sebastian Edwards and others have examined cases across Latin America. The pattern is consistent and quantified:
Chile (1970–1973): Rapid monetary financing of large deficits. Inflation exceeded 500 percent by 1973. Real wages fell approximately 39 percent over the period.
Peru (1985–1990): Similar policy mix. Inflation reached hyperinflationary levels, peaking near 7,000–8,000 percent. Real wages declined about 41 percent.
Venezuela (from the late 1990s onward): Extensive monetary financing of spending. Inflation reached extreme hyperinflationary rates (official figures showed increases on the order of 130,000 percent in one year). Real wages suffered severe declines.
Argentina: Multiple episodes across decades. Chronic deficits, monetary financing, and rhetoric about reactivating idle capacity produced repeated high-inflation crises, currency instability, capital controls, and black markets for foreign exchange. Long-run average inflation has been extremely high.
In these experiments an initial boom in activity and wages was typically followed by bottlenecks, accelerating inflation, price and exchange controls that failed, output contraction, and lower real wages than at the start. Policymakers used language strikingly similar to contemporary MMT arguments about unused capacity and the irrelevance of conventional financing constraints.
MMT advocates often reply that these countries lacked full “monetary sovereignty.” That reply concedes a central practical limitation: the benign results promised by the theory depend on stringent institutional and credibility conditions that most real economies do not fully satisfy. When those conditions are imperfect, the predicted results do not appear.
5. The Job Guarantee in Practice
A prominent MMT policy proposal is a permanent job guarantee—an open-ended offer of public employment at a living wage intended to eliminate involuntary unemployment and act as a labor buffer stock.
Practical difficulties are substantial. Because the program is designed to expand and contract with the private cycle, the work assigned must remain highly flexible. This pushes it toward low-skill or make-work activities. Claims that participation will preserve skills and improve private-sector employability are hard to sustain if the jobs are widely understood to be light or optional. Inflation risks arise if the program wage competes with private pay and raises labor costs more broadly.
Argentina’s Jefes program after the 2001–2002 crisis is frequently cited by MMT writers. In practice it was far more limited than the ambitious proposal: restricted eligibility, low pay, and in many cases little actual work required. Large numbers of participants received payments without performing meaningful labor. The program was later shifted toward pure income support. It did not function as the robust, skill-preserving, inflation-stabilizing institution described in the theoretical literature.
6. Description Versus Prescription — and the Political Economy Problem
Even granting MMT’s accounting observations, the rhetorical effect of the theory matters. By repeatedly framing financial constraints as largely illusory or “self-imposed,” it reduces the political cost of large new spending. Conventional analysis treats tax increases and rising debt as visible trade-offs that create some restraint. MMT’s framing weakens those restraints.
Multiple critics — including the Bank of France economists noted above and analysts distinguishing “scholarly” from “pop” MMT — argue that the theory often slides from positive description into a normative project. The insistence that “this is already how the system works” serves to make radical policy changes appear frictionless. When institutional details contradict the claim, the fallback is that the rules should be changed. The practical result is a framework that lowers perceived constraints on spending while maintaining the posture of merely describing reality.
Once the political system internalizes the idea that the government cannot run out of money and that inflation is the only limit — and that inflation can be managed mainly by taxing or by targeting “idle” resources — the incentive to spend rises. Historical episodes show that the inflation constraint is often recognized too late, after expectations have shifted and real damage has occurred.
Conclusion
MMT contains accurate accounting statements. Government deficits equal non-government financial surpluses. A currency issuer is not constrained in the same mechanical way as a household. Inflation is a real limit. These points were already understood in mainstream economics.
What MMT adds are stronger claims: that current spending procedures already amount to unconstrained money creation, that deficits reliably improve private-sector real wealth, that inflation appears only at a clearly identifiable capacity ceiling, and that large programs such as a job guarantee can be introduced with manageable side effects. These stronger claims do not survive contact with institutional detail, formal empirical tests (including DSGE rejection against U.S. data), or the historical record of high inflation and falling real wages in multiple countries.
When policies in the spirit of “spend first, treat financial limits as largely self-imposed, and rely on real-resource constraints that prove difficult to measure or enforce in real time” have been followed, the repeated results have been high inflation, currency instability, and lower real wages. The theory remains attractive because it appears to dissolve hard trade-offs. The evidence from institutions, data, formal modeling, and history shows that the trade-offs reassert themselves — usually through rising prices and diminished real incomes.