Why the Next One Is Worth Less: Understanding Marginal Utility
The more of something you already have, the less you usually value one more unit of it. That simple idea explains a remarkable amount about human choice, scarcity, prices, and money. Economists call it marginal utility.
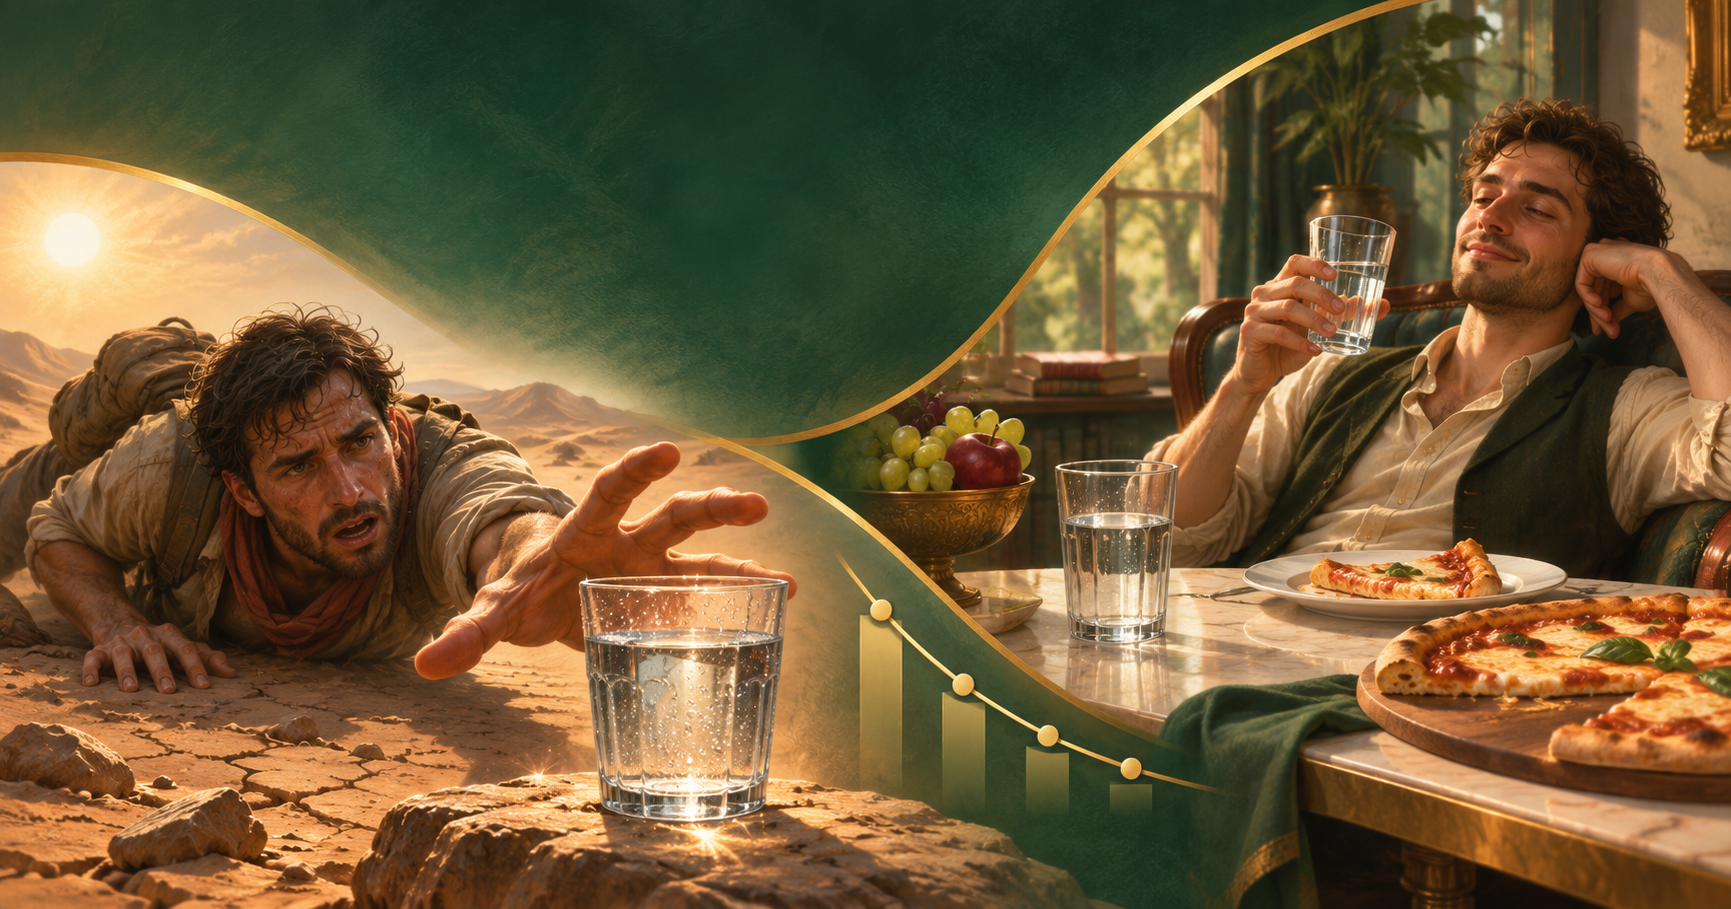
Imagine you have been walking through the Sahara for eight hours. You are exhausted, overheated, and badly dehydrated when someone offers you a glass of water. At that moment, the glass may be worth more to you than your wallet, your phone, or even your shoes. Now imagine the same glass sitting on your kitchen counter after dinner when you are already well hydrated. You might barely notice it.
The water did not change. You did.
Value Is Not Inside the Object
Economic value is not a physical property contained within a good. A glass of water does not have a fixed quantity of value embedded in its molecules. Its value depends on who is evaluating it, the circumstances that person faces, the alternatives available, and how much of the good they already possess.
The important question is therefore not simply, “How useful is water?” Water is essential to life. The economic question is, “How valuable is one additional unit of water to this person right now?”
That additional unit is the marginal unit. Much of economic decision-making occurs at that margin.
Suppose you order a pizza while extremely hungry. The first slice is excellent. The second is still very satisfying. The third is good. By the fourth or fifth, your desire for another slice has fallen sharply. Nothing necessarily changed about the pizza; what changed was the value you place on the next slice.
This is diminishing marginal utility: as you acquire more units of many goods, the additional satisfaction gained from one more unit tends to decline.
Why the Last Unit Matters
Imagine you have five gallons of water and use them for drinking, cooking, hygiene, cleaning, and watering flowers. If one gallon disappears, you probably do not give up drinking water. You give up the least important use currently being satisfied—perhaps watering the flowers.
That is the core insight. The value of an additional unit is tied to the least urgent want that the available supply can still satisfy.
This helps explain one of economics' oldest puzzles: why can diamonds be expensive while water is cheap?
Water is obviously more useful to human survival than diamonds, yet under ordinary conditions a diamond may cost thousands of dollars while a glass of water costs almost nothing. The puzzle arises only if we assume price should reflect a good's total usefulness. People do not normally choose between all the water in the world and all the diamonds in the world; they choose between individual additional units.
Where water is abundant, the next glass usually satisfies a relatively low-priority want. Diamonds are much scarcer, so the marginal unit is generally valued more highly. Put the same person in a desert and the ranking reverses immediately.
The Marginal Revolution
This insight became central to the Marginal Revolution of the nineteenth century. Carl Menger published Principles of Economics in 1871, while William Stanley Jevons and Léon Walras independently developed related marginal approaches around the same period.
Their work greatly weakened the explanatory force of older theories that tried to ground value primarily in labor or production cost.
Karl Marx's economic system, for example, relied heavily on a labor theory of value. But marginal analysis exposed a fundamental problem: labor expended on a good does not compel anyone to value the result. A person can spend a thousand hours producing something nobody wants, and those thousand hours do not magically make the product valuable.
Likewise, a drowning man has no use for a diamond, while a person dying of thirst may value water above nearly everything else. The amount of labor embodied in either object does not explain those choices.
Production costs still matter enormously because they influence whether a good can profitably be supplied. But they do not independently create consumer value. Marginal utility offered a far stronger explanation of why people actually exchange goods at different valuations, which is one reason older labor-based theories lost much of their standing in mainstream economics.
Prices Carry Information
Marginal utility also helps explain why market prices are not arbitrary numbers attached to products. Prices emerge from the interaction of buyers and sellers, each making decisions under scarcity and choosing at the margin.
If a drought sharply reduces the supply of tomatoes, prices tend to rise. That higher price tells consumers the good has become relatively scarcer and gives them an incentive to economize. At the same time, it gives producers a stronger incentive to grow, transport, import, or substitute additional supply.
A price therefore compresses enormous amounts of dispersed information into a single signal. It reflects changing scarcity, demand, alternatives, expectations, and opportunity costs without any one person needing to know the entire story.
This is also why price controls can create serious distortions. If a scarce food would otherwise sell for $10 but the government imposes a maximum price of $5, the legal price has changed while the underlying scarcity has not. Consumers have less incentive to conserve, while producers may have less incentive or ability to supply the product profitably. The result can be shortages, rationing, waiting lines, lower quality, or black markets.
Venezuela's extensive price controls during the 2000s and 2010s were one factor among several that contributed to severe shortages and distorted production incentives. The broader lesson is simple: a government can command a price, but it cannot command scarcity out of existence.
Marginal Utility and Money
Marginal utility becomes especially interesting when applied to money. People value money because it provides liquidity, allows future purchases, settles debts, and protects against uncertainty.
Someone with only $50 available may value another $100 enormously. Someone with $50 million may barely notice it. The dollars are identical; their marginal utility is not.
This also helps explain why the distribution of newly created money matters. If new money enters the economy through particular banks, borrowers, government contractors, financial markets, or other early recipients, those people can act on the new purchasing power before every price in the economy has adjusted.
Later recipients may encounter a different price structure. Money does not simply fall evenly across society. Its effects depend partly on who receives additional units first, when they receive them, and what they purchase with them.
That connects marginal utility directly to monetary economics and to the Cantillon Effect.
Every Choice Happens at the Margin
Should you work one more hour? Buy one more share? Eat one more slice? Save one more dollar? Borrow another thousand dollars? Produce one more unit?
Each decision compares the expected benefit of an additional unit against the next-best alternative that must be sacrificed to obtain it.
That is why marginal utility is so powerful. It is not an abstract curiosity confined to economics textbooks. You experience it constantly: the first glass of water when thirsty, the second cup of coffee, the fourth slice of pizza, the extra hour of sleep, the hundredth dollar when broke, and the hundredth dollar when wealthy.
The principle is the same each time:
The value of an additional unit depends on the importance of the next want that unit can satisfy.
Once you understand that, the question “What is this worth?” becomes incomplete.
The better question is:
What is one more worth, to whom, under what circumstances, and compared with what alternative?
That is marginal utility.