Chair's handbook Close
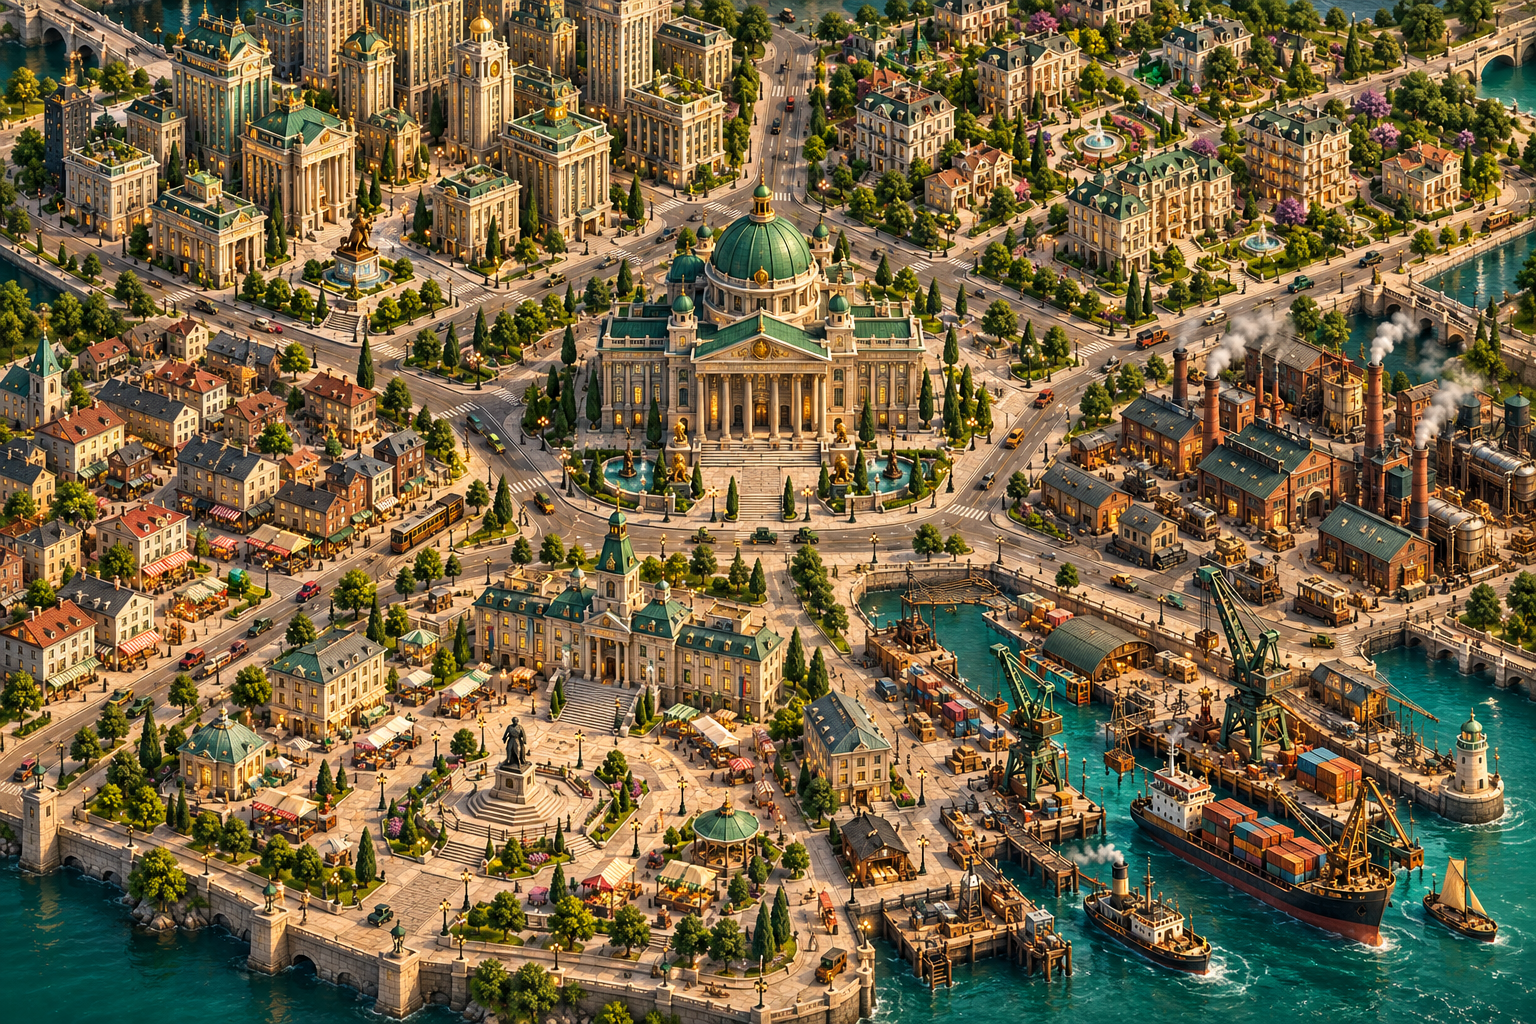
How to preserve your mandate Review conditions. Tap districts, check banks, and read the policy pipeline.Choose your package. Set rates, asset operations, bank standards, and a public statement.Commit the quarter. Markets react, previous policies take effect, and an economic event may occur.Resolve the event. Each response has stated costs. Your next meeting opens after the response.Complete five years. The final grade is the average of all quarterly scores. Aim for 65 or above, then finish with a stable final year: average score at least 65, inflation 0–4%, and unemployment no more than 7%.Pieces and residents Your gold-and-emerald chairman piece moves when you inspect a district and visits the affected district when a crisis appears. It is an inspection marker. Tap Mira, Elias or Nadia on the city or council strip to hear their views and ask follow-up questions about your policy hand, risks and crises. The chairman delivers your selected public statement in a speech bubble; Replay statement brings it back. Advisors react to current conditions, but asking questions does not change policy or advance time. Shoppers, workers, dockhands and bank customers follow local sidewalks; queues and protest banners reflect conditions. Vehicles follow traced street lanes, while gold tokens illustrate credit flows. These visual pieces do not change the economic results.
Five equally weighted goals Price stability rewards inflation near 2%. Employment rewards low unemployment and positive growth. Banks rewards resilience and penalizes failures. Households rewards real purchasing power and a smaller distribution gap. Trust combines confidence and social stability.
Consequences on the board Inflation above 4% builds household budget strain. Above 5%, damage accelerates; consecutive high-inflation quarters amplify it further. Strain lowers the household goal and increases unrest, even if real income has barely changed. After inflation falls to 4% or below, strain eases gradually rather than disappearing. Open the household or public-square briefing to see its level and duration.
Asset heat above 72 can cause a correction. Demonstrations above 62 interrupt commerce; strikes above 82 interrupt production. Disruptions settle after the quarter's event response. Bank capital below 28 or liquidity below 30 triggers a crisis. Unrest of at least 96, confidence of 8 or below, or all banks failed counts as critical stress. Two consecutive critical quarters end your term.
The model's assumptions This is a stylized educational economy. Rate changes spread their demand effects over three quarters, alongside a sustained rate-level effect. The real rate is the policy rate minus inflation; this model assumes a neutral real rate of 1%. Below it, demand, lending and asset prices receive ongoing support. Above it, demand faces ongoing restraint. Inflation fades slowly and low unemployment increases price pressure. A 0% rate can help a slump but can overheat a busy economy if held too long. Purchases add reserves, influence market prices, and support demand. Bank lending responds to demand, funding, and supervision; reserves do not mechanically multiply into a fixed amount of lending.
Supply shocks can raise prices while reducing production. A fictional exchange-rate index responds to rates, confidence, inflation, and asset operations; depreciation adds import-price pressure. Wages adjust imperfectly, so workers, savers, and asset owners can experience different outcomes.
Real purchasing-power indices begin at 100. Worker income changes approximately by (annual wage growth − inflation) ÷ 4 each quarter. Savers earn 65% of the policy rate in this model. Asset owners respond to asset prices. The distribution gap is the positive difference between the asset-owner and worker indices; it is a game indicator rather than a real-world inequality measure.
Saving and replay Your game resumes on this browser, including unresolved events. Export and load JSON saves to move between devices. Four scenarios have different starting conditions. Shocks vary between new games; a save retains the random sequence.
Return to the meeting